
By Janet Salmon
Universal Parallel Accounting (UPA) extends ledger-specific accounting to inventory valuation, product costing, and Actual Costing in SAP S/4HANA. This guide explains legal and group valuation, parallel currencies, and ledger-specific material costs.
Scope and updates: This article explains UPA inventory accounting and product costing introduced with SAP S/4HANA 2022, with later-release updates identified where relevant. Availability and migration restrictions depend on the release and deployment. The original article is by Janet Salmon; subsequent editorial updates are by ERPCorp.
Table of Contents
- Inventory Accounting
- Universal Parallel Accounting & Product Costing
- Unconsolidated Views
- Consolidated View
- Ledgers in Universal Parallel Accounting (Figure 2)
- Parallel Currencies for Product Costing
- Currency Settings for Group Valuation Ledger (Figure 3)
- Material Valuation
- Standard Cost Estimates
- Actual Costing
- Balance Sheet Valuation
- Conclusion
- Glossary
Inventory Accounting
Universal Parallel Accounting (UPA) in SAP S/4HANA introduces ledger-specific valuation for inventory accounting and product costing. It enables organizations to manage parallel accounting principles, material prices, standard costs, actual costs, and group valuation across multiple ledgers and currencies.
This guide explains how Universal Parallel Accounting affects:
- Material Valuation
- Product Cost Planning
- Actual Costing
- Balance Sheet Valuation
Universal Parallel Accounting & Product Costing
UPA offers two types of parallel valuations for product costing: unconsolidated views, which represent different legal valuations, and a consolidated view, which is a group valuation. The differences are illustrated in the four UPA Use Cases in Figure 1.
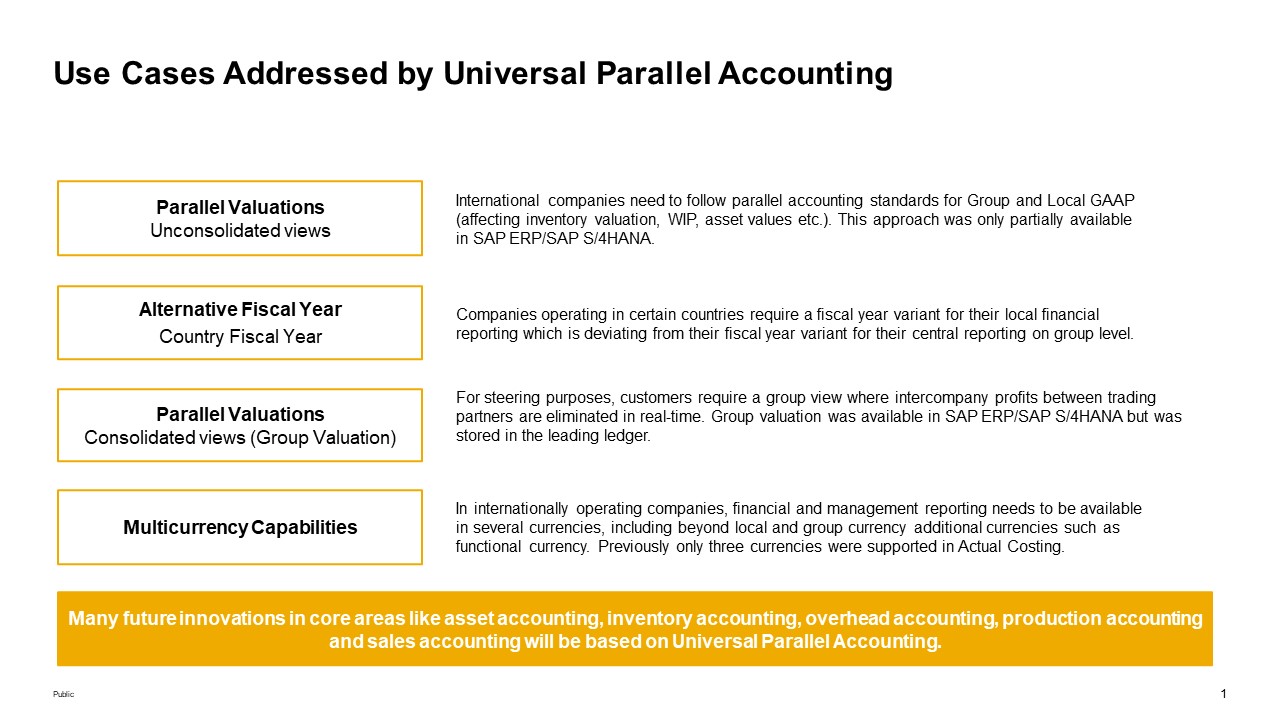
Figure 1: Universal Parallel Accounting Use Cases
Unconsolidated Views
Based on corporate and local accounting principles, the unconsolidated views focus on valuing materials differently. Typically, one common accounting principle (such as IFRS) is used in all countries, alongside many different accounting principles based on local GAAPs in various countries. Local inventory valuation requirements should be evaluated separately from the decision to activate SAP Actual Costing. You may be familiar with this approach if you've worked with the business function Parallel Cost of Goods Manufactured FIN_CO_COGM.
The new approach is more comprehensive as it enables you to carry the same material with multiple legal prices and standard costs and to calculate production variances and contribution margins in each ledger. This provides an end-to-end view of product profitability that can vary depending on the underlying accounting principles.
Consolidated View
With the consolidated view, the focus is on achieving a group view for intercompany value flows, distinct from transfer prices used by affiliated companies as they trade among one another at arm's length. This approach, known as group valuation, differs from legal valuation because it excludes transfer pricing.
With UPA, we introduce a consolidation-like approach in which the intercompany revenues and Cost of Goods Sold COGS are eliminated in a separate ledger whenever an intercompany boundary is crossed within the group, such as when a manufacturing company sells to a distribution center or the distribution center sells to the selling company that manages the business with the final customer. The at-cost valuation continues to be supported for the valuation of intercompany goods movements, ensuring that profit in inventory is excluded in the group view.
Profit center valuation is available with Universal Parallel Accounting as of SAP S/4HANA 2023 and is implemented using a separate ledger.
Customers who used group and profit center valuation in the past stored these additional valuation views in the leading ledger (multi-valuation ledger). The new approach is based on single valuation ledgers, where the unconsolidated views are separated by ledger (as before), and an additional single valuation ledger is enabled for group valuation. Figure 2 provides a schematic view of the new approach, showing two unconsolidated views (or legal valuations) in ledgers 0L and 2L and one consolidated view (or group valuation) in ledger 4G.
If you are not using UPA, the previous multi-valuation ledger recommendation still applies (see SAP Note: Implementing Transfer Prices). However, with UPA, the new ledger for group valuation uses the same accounting principle and fiscal year variant as ledger 0L (previously, Asset Accounting did not support using the same principle in multiple ledgers). The ledger settings are delivered as best practice business content.
UPA can be implemented in a new system or migrated to in an existing SAP S/4HANA system, provided the migration prerequisites are met. Existing systems require prechecks and a migration project before UPA can be activated.
Migration scope: Availability of a UPA function does not mean that an existing system using that function can migrate directly. For example, SAP S/4HANA 2025 FPS01 migration prechecks exclude group valuation and profit center valuation from the documented migration scenario. Check the prerequisites and restrictions for your target release before planning migration.
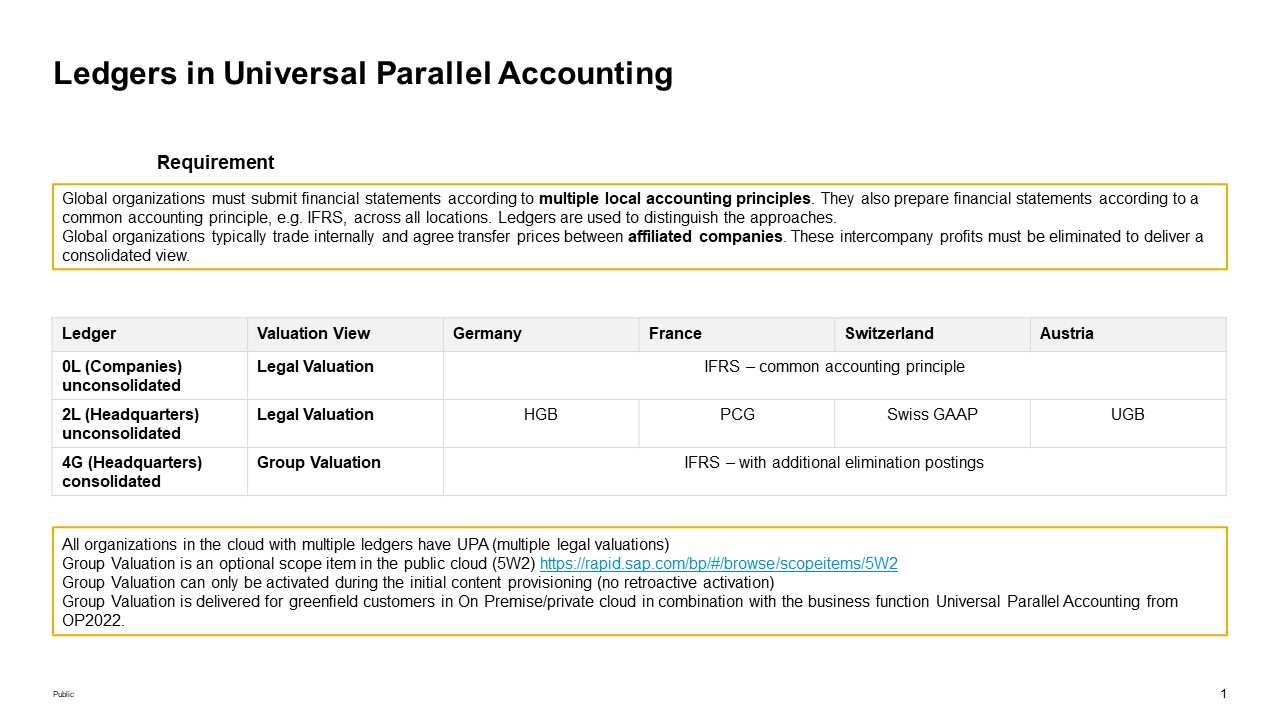
Figure 2 Ledgers in Universal Parallel Accounting
Parallel Currencies for Product Costing
Universal Parallel Accounting supports up to 10 currencies across ledgers and accounting processes. For Product Cost Controlling, these currencies are integrated with Material Ledger and support parallel valuation of material prices, product costs, actual costs, inventory values, and other manufacturing costs.
In SAP ERP, the currency and valuation profile determined the currencies and valuation views used for transfer pricing. Currency and valuation type 31 represents group valuation in group currency, while 11 represents group valuation in company code currency.
The leading currency was used to determine which currency would value the intercompany goods transfer in combination with the price condition KW00. The other currency was derived using currency conversion at the time of posting.
The new approach defines the currencies used in the group ledger via the ledger settings, and the currency and valuation profile become obsolete with UPA. Figure 3 shows a sample ledger for group valuation with currency types 11 (local currency) and 31 (group currency) and various additional currencies. The new approach treats all currencies equally, allowing you to have a consistent group view in multiple currencies. In other words, an intercompany goods movement will be valued using all currencies active in the group valuation ledger, rather than converting from the leading currency. Note that currency type 20 is no longer supported.
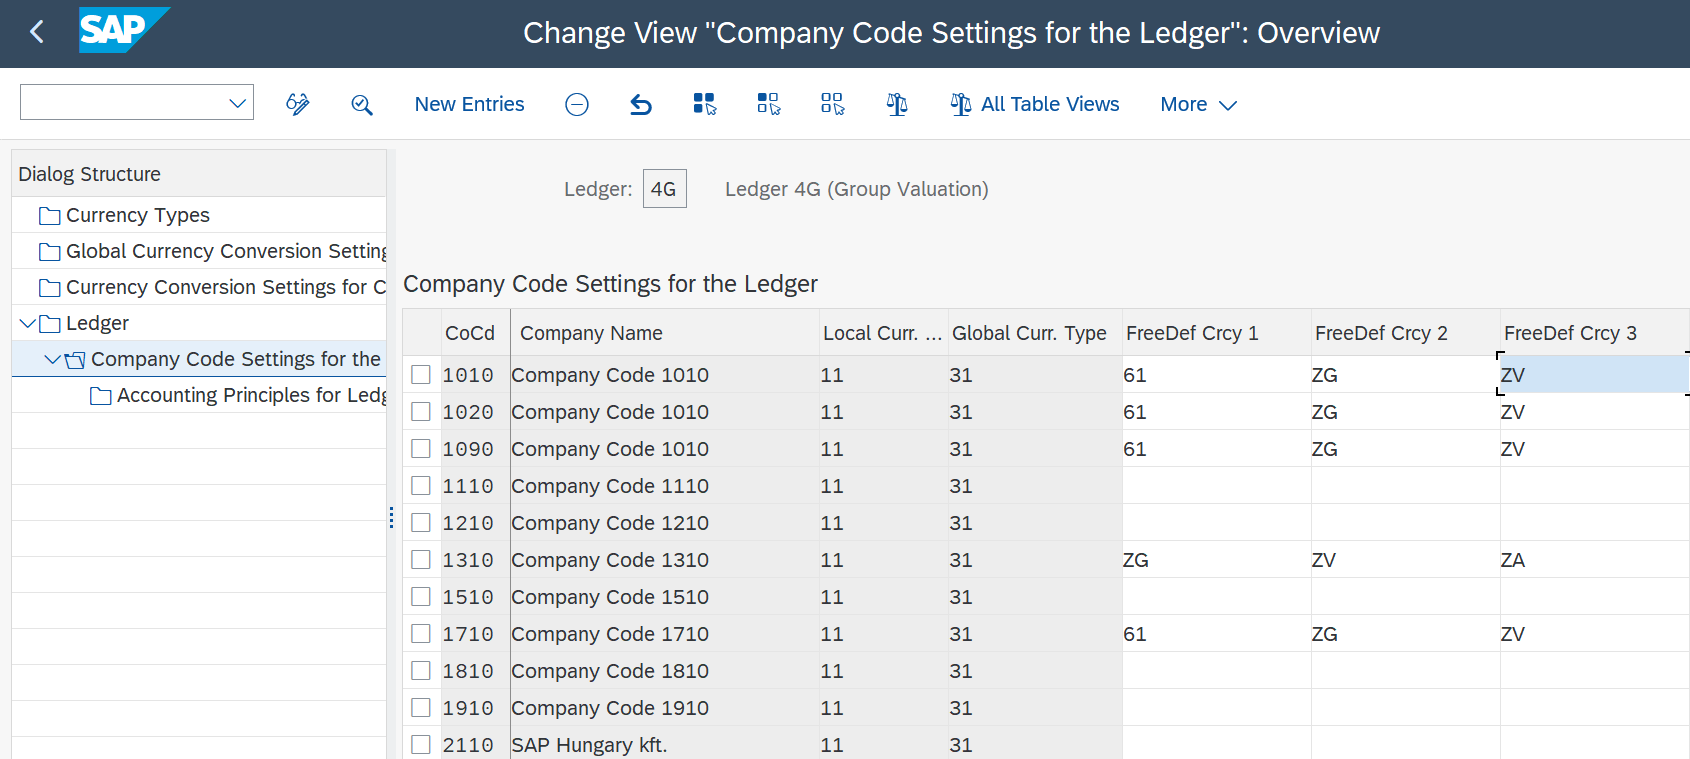
Figure 3 Currency Settings for Group Valuation Ledger
Material Valuation
Material Ledger is mandatory for inventory valuation in SAP S/4HANA, while Actual Costing remains optional. Additional valuation views require the appropriate configuration; they are not enabled merely because Material Ledger is active. With UPA, material prices can be maintained by ledger to reflect different accounting principles and supported valuation perspectives. Planned, commercial, and tax prices have distinct purposes and should not be confused with the price used to value a goods movement.
See our comparison of standard price and moving average price for background on material price control.
With Universal Parallel Accounting, material prices can be maintained separately by ledger and used for the initial valuation of goods movements, variance calculation in Production Accounting, and contribution margin calculation in Margin Analysis. UPA stores ledger-specific material price information in the material price table FMLT_PRICE. Figure 4 shows the Change Material Prices app with various price types (STDPR, INVPR, FUTURE, and so on) and selection by ledger.
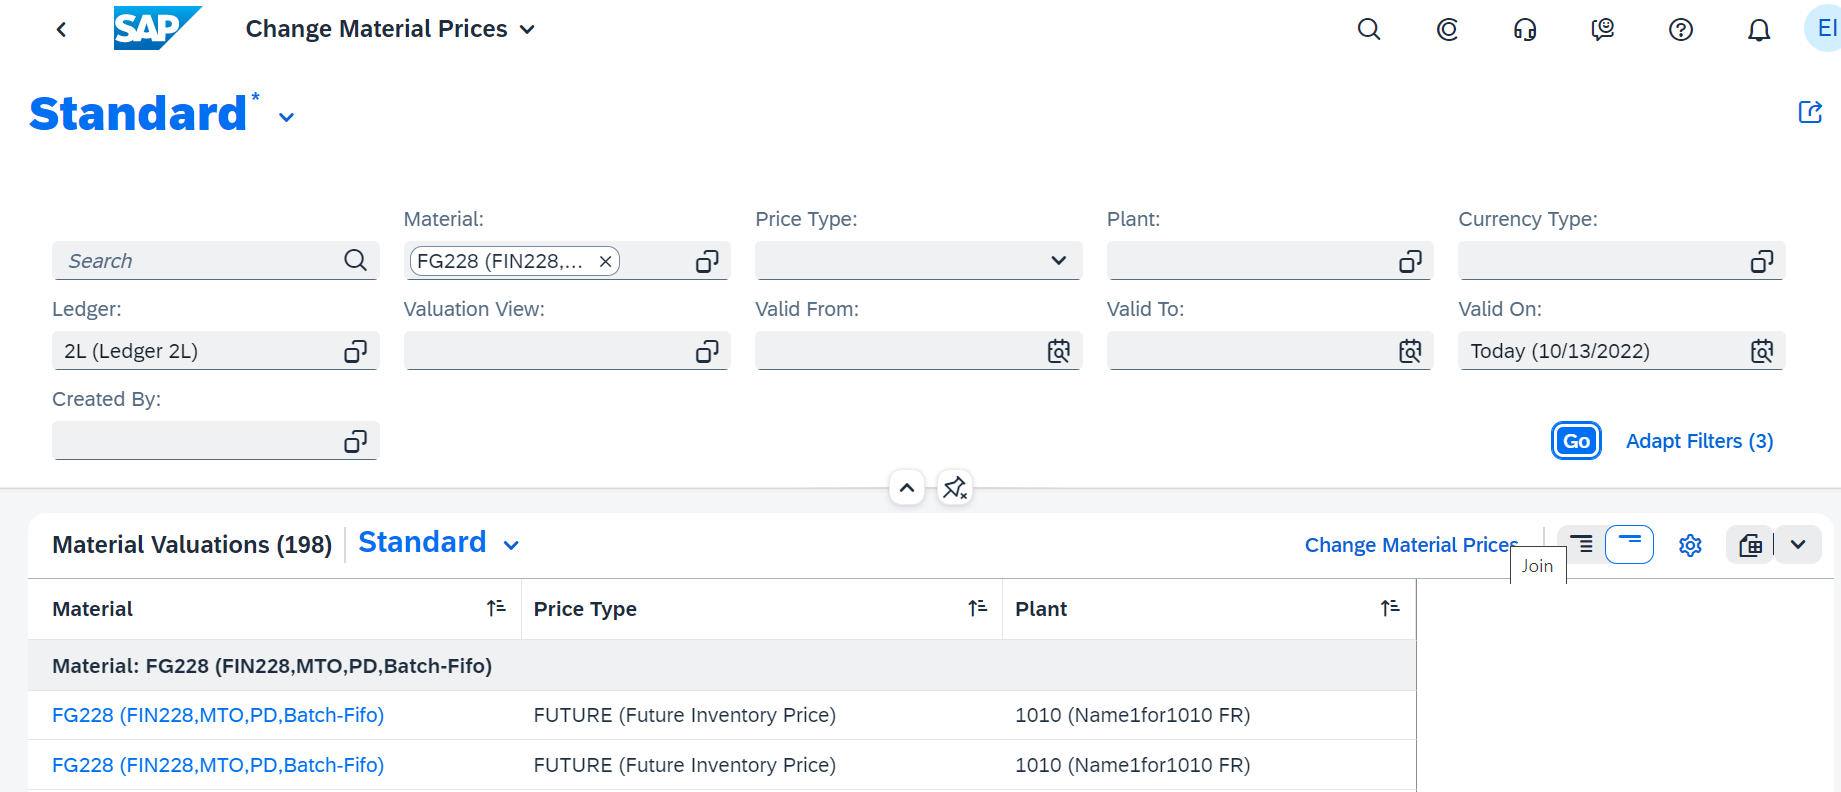
Figure 4 Change Material Prices app
The ability to manage ledger-specific material prices applies to both raw materials and trading goods, where the purchase price may be impacted by additional freight and duty costs, and finished goods, where the cost of goods manufactured may be affected by the different assumptions behind the asset values reflected in the activity prices and overhead rates.
Material inventory prices can also be updated in mass using the Upload Material Inventory Prices app, as shown in Figure 5. Prices can be updated for individual ledgers or transferred to other ledgers.
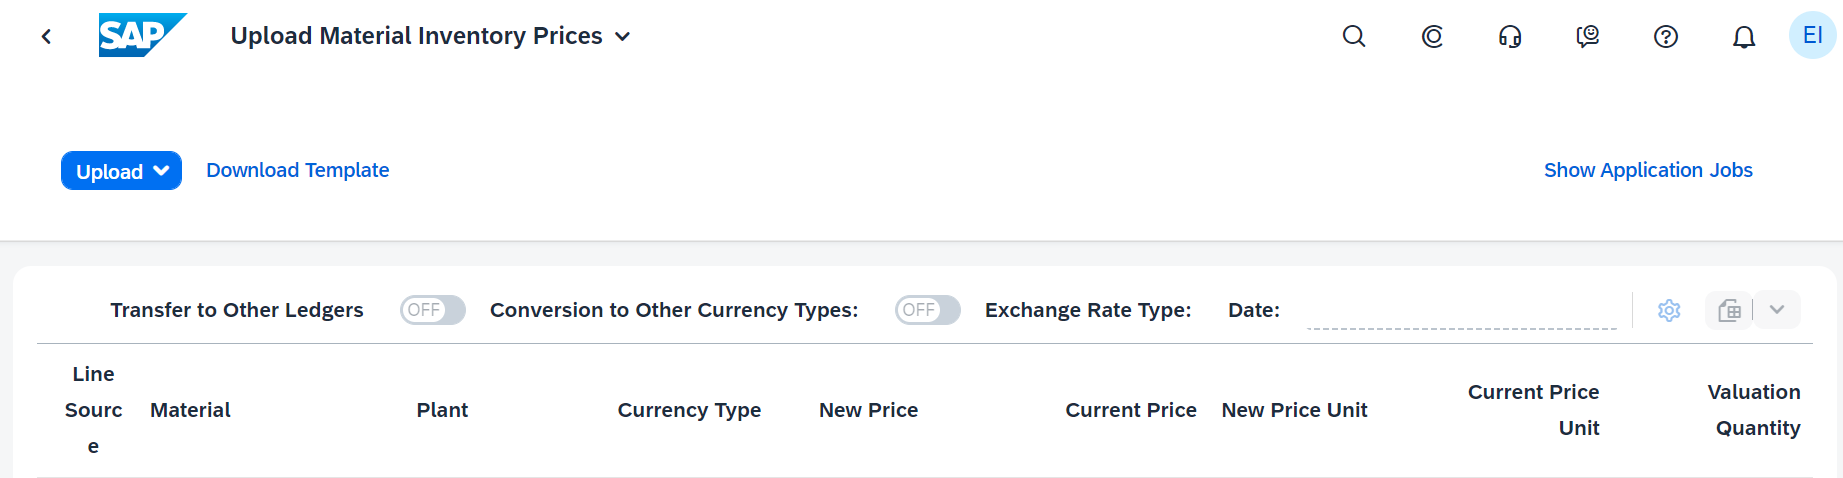
Figure 5: Upload Material Inventory Prices App
Material prices can be maintained and displayed by ledger using SAP Fiori apps and material master transactions. For detailed analysis, Material Price Analysis (transactions CKM3 and CKM3N) provides information about goods movements, price changes, and material settlements by ledger. Figure 6 shows Material Price Analysis for material FG228 in ledger 4G. The Curr./Valuation field allows you to analyze the currencies and valuation views configured for the selected ledger.
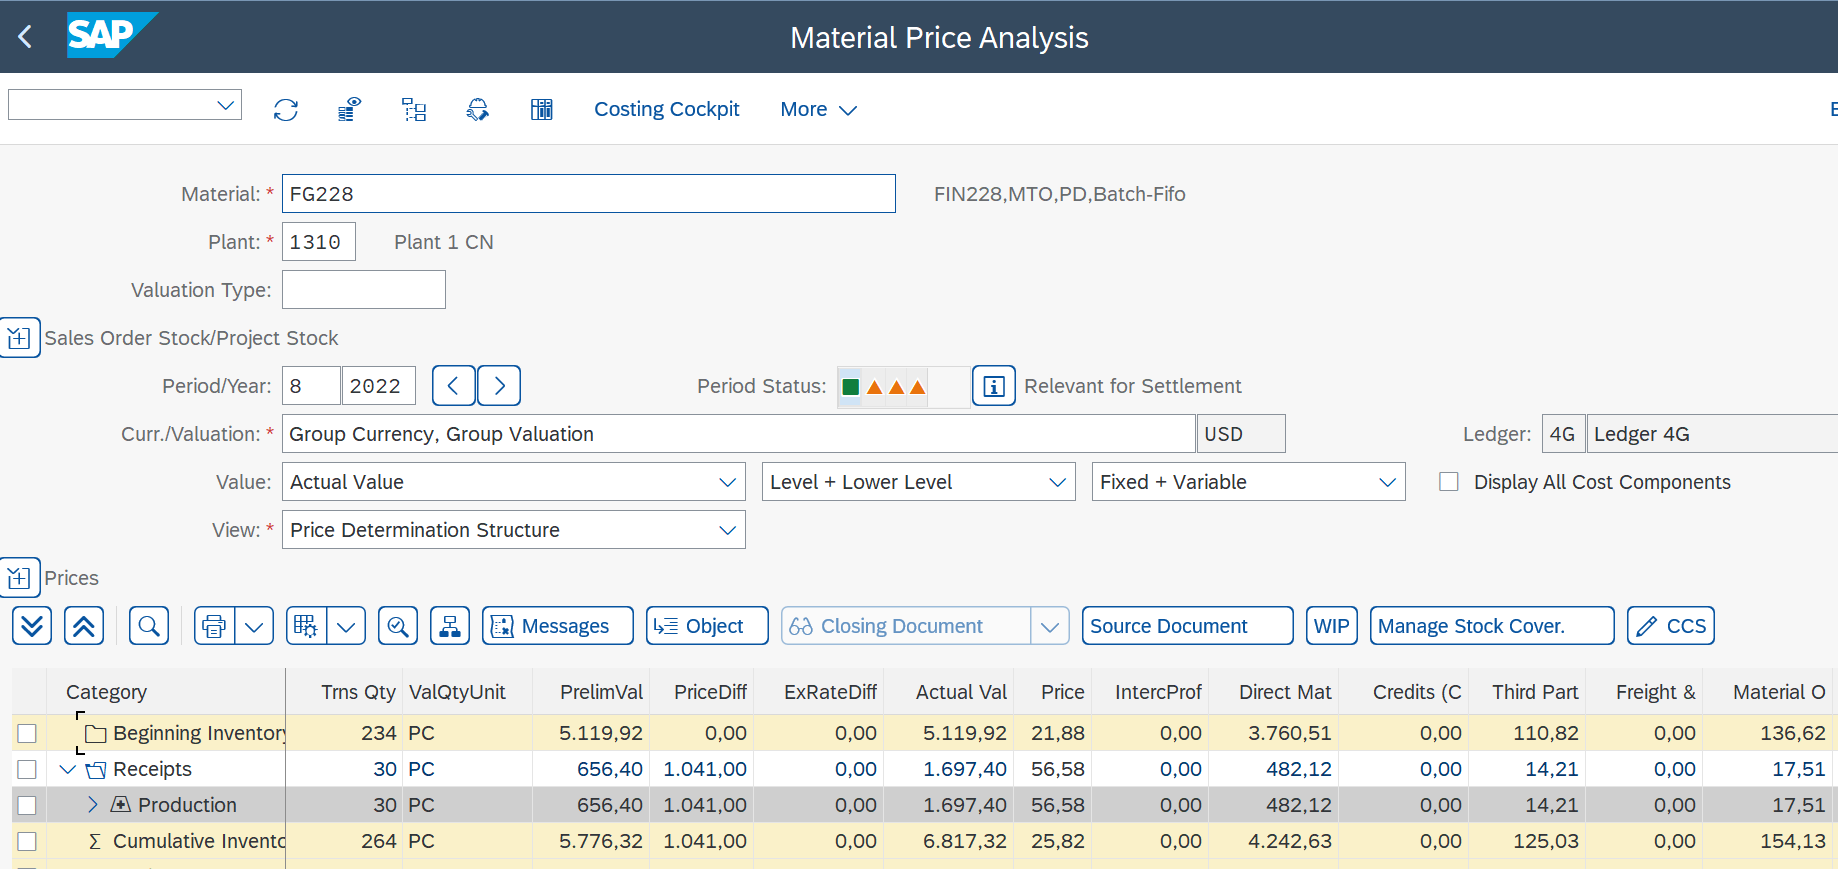
Figure 6: Material Price Analysis (Transaction CKM3N) in Group Valuation Ledger
Standard Cost Estimates
Standard cost estimates provide the standard costs used for the initial valuation of inventory when goods movements are posted. With UPA, standard cost estimates can be created, marked, and released by ledger. Figure 7 illustrates the Manage Material Valuations app and the Standard Cost Estimates tab.
For legal valuation, SAP provides ledger-specific costing variants such as P00L for ledger 0L and P02L for ledger 2L. A costing variant without a ledger assignment can also be used to update the same standard cost across multiple ledgers. If different accounting principles require different costs, ledger-specific costing variants can be used instead.
Group valuation continues to use a separate group cost estimate because it represents a different valuation perspective. Group ledger 4G supports the calculation of standard prices from the group valuation perspective and eliminates intercompany profit from the group cost of goods manufactured.
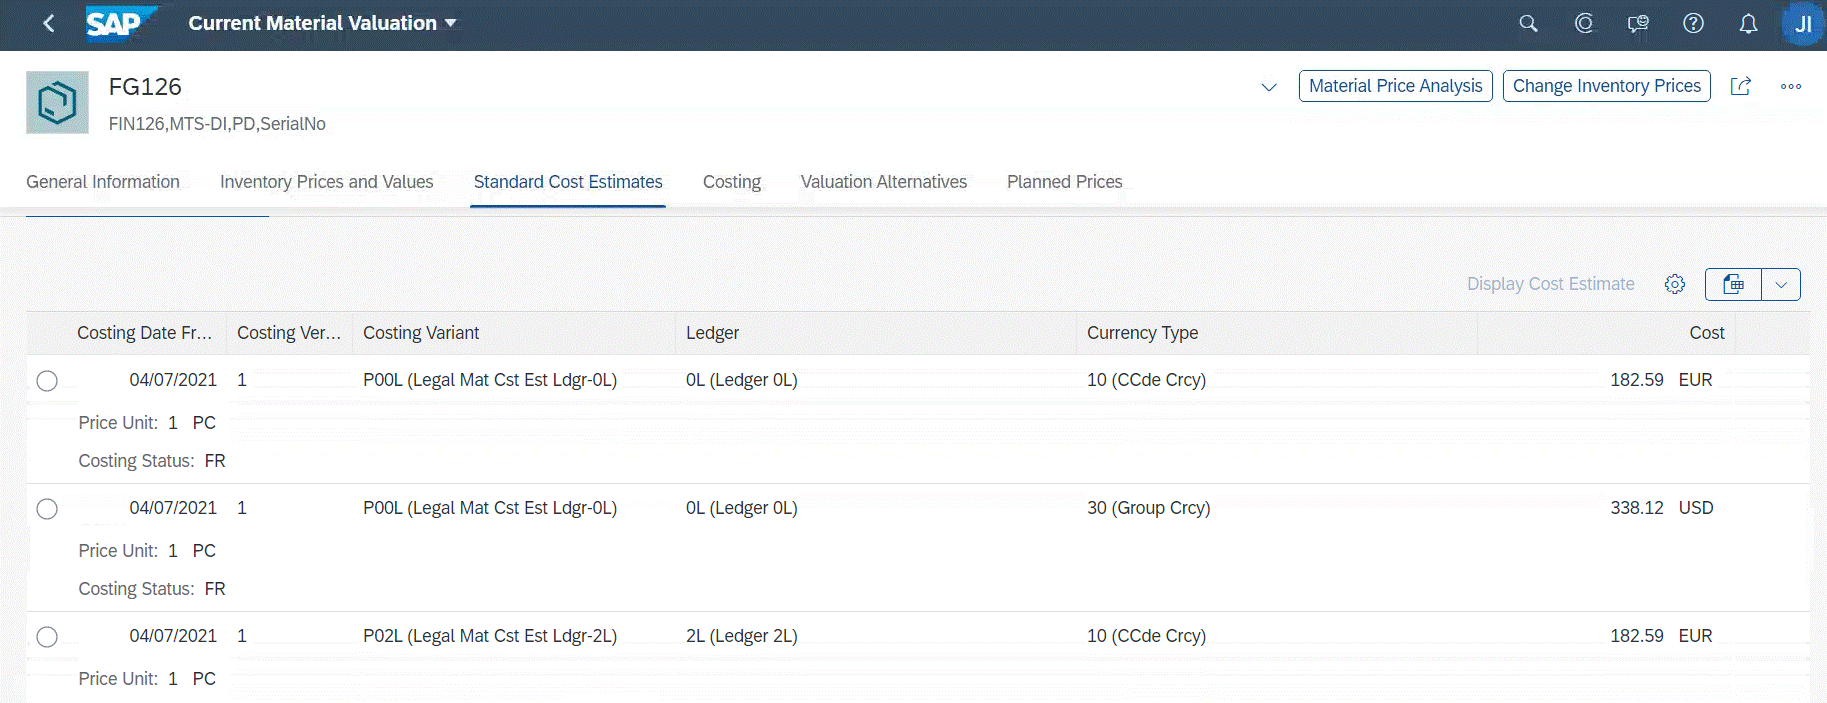
Figure 7: Current Material Valuation – Standard Cost Estimates
Figure 8 illustrates how costing variants and costing types are assigned to ledgers. Existing costing variants can continue to support common costs across multiple ledgers, while ledger-specific costing variants allow different standard costs to be calculated and released for individual ledgers.
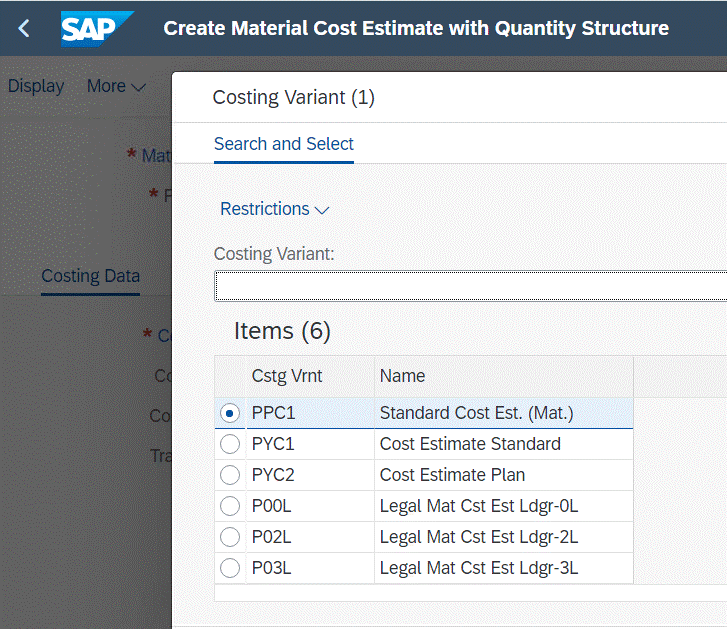
Figure 8: Sample Costing Variants
With UPA, the ledger is included in the costing and valuation data of standard cost estimates (transactions CK11N and CK13N) and costing runs (transaction CK40N). This allows costing runs to be managed separately by ledger—for example, by company code for legal valuation or across company codes for group valuation. Material cost estimates are calculated in controlling area and object currencies and translated into the additional currencies configured for the ledger when the standard cost is released.
Standard cost estimates must also be marked and released separately for each ledger using Transaction CK24. Figure 9 shows the company code, ledger, and costing variant used when releasing the cost estimates. Releasing a standard cost estimate updates the material's standard price for the relevant ledger and can result in revaluation of existing inventory. The released standard costs also provide the basis for ledger-specific production variances and cost of goods sold. To learn more about how production variances are calculated with UPA, see Shuge Guo's blog, Production Accounting for Universal Parallel Accounting.
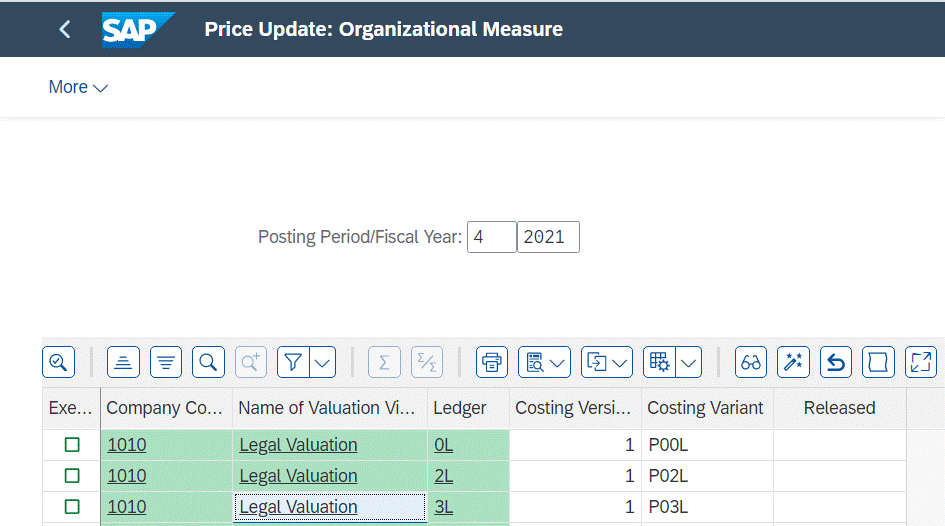
Figure 9: Marking and Releasing Cost Estimates (transaction CK24)
For make-to-order scenarios, UPA also supports ledger-specific sales order cost estimates. SAP provides ledger-specific costing variants PB0L for ledger 0L, PB2L for ledger 2L, and PB3L for ledger 3L, allowing sales order items to be costed according to the accounting principle assigned to each ledger.
In intercompany scenarios, revenues and cost of goods sold are posted according to the valuation approach of the relevant ledger. In the legal valuation ledger, intercompany transactions include the intercompany margin. In the group valuation ledger, this intercompany margin is eliminated so that the transaction is represented from the group perspective. Valuation differences arising from intercompany transactions are posted to a valuation clearing account, as shown in Figure 10.

Figure 10: Group Valuation with Elimination of Intercompany Business in Delivering Company
As goods move from the delivering company to the selling company, the goods movement is valued using the group standard cost and recorded in the group valuation ledger (4G), as shown in Figure 11. Because the group standard cost excludes intercompany profit, no separate profit elimination is required for the inventory valuation.

Figure 11: Group Valuation with At-Cost Valuation of Intercompany Goods Movement
This article focuses on the inventory accounting implications of UPA rather than the complete Advanced Intercompany Sales process. For more information about Advanced Intercompany Sales and stock transfers, refer to the current SAP documentation.
Actual Costing
With UPA, Actual Costing is performed using ledger-specific actual costing runs (Ledger Runs). A separate ledger run is required for each ledger relevant to Actual Costing. This allows Actual Costing to be performed according to the accounting principles and valuation requirements represented by each ledger, including group valuation where applicable.
For background on the material master settings, see Material Price Determination in SAP S/4HANA Material Ledger. These settings provide background on conventional Material Ledger; the ledger-specific UPA process is described here.
The costing run CKMLCP is created using a run template (see Figure 12) that contains the link to the ledger and associated company codes and determines whether the run applies to a single period or year-to-date. This choice determines whether Actual Costing is calculated period-by-period or cumulatively over the year.
Because run templates are ledger-specific, Actual Costing can be executed independently for each ledger. The Company Code Assignment tab determines which company codes are included in the ledger run. All plants belonging to an assigned company code are included in the run. This also allows group valuation to be processed independently from legal valuation.
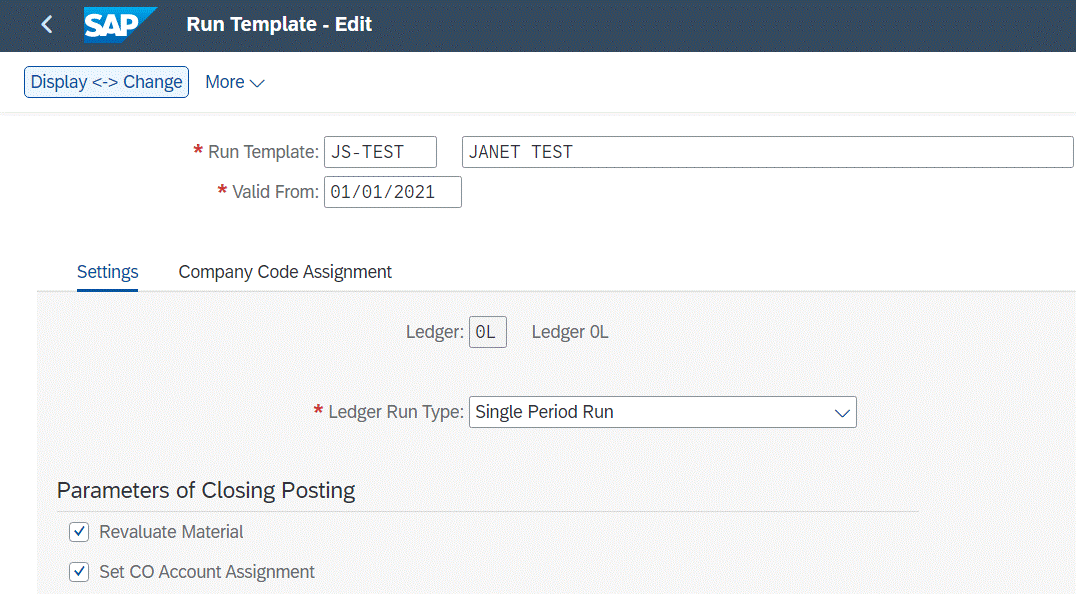
Figure 12: Template for Costing Run
The costing run shown in Figure 13 references the run template to determine the ledger, company codes, and Ledger Run Type. Actual costs can therefore be calculated and inventory and consumption values updated independently for each ledger. For group valuation, a separate ledger run can be executed for the group valuation ledger.
With UPA, the previous concepts of periodic actual costing runs and alternative valuation runs are replaced by ledger-specific Ledger Runs. A Single Period Run calculates actual prices for one period, while a Year-To-Date Run calculates cumulative actual prices from the first period of the fiscal year through the selected period. Each ledger run is processed independently.
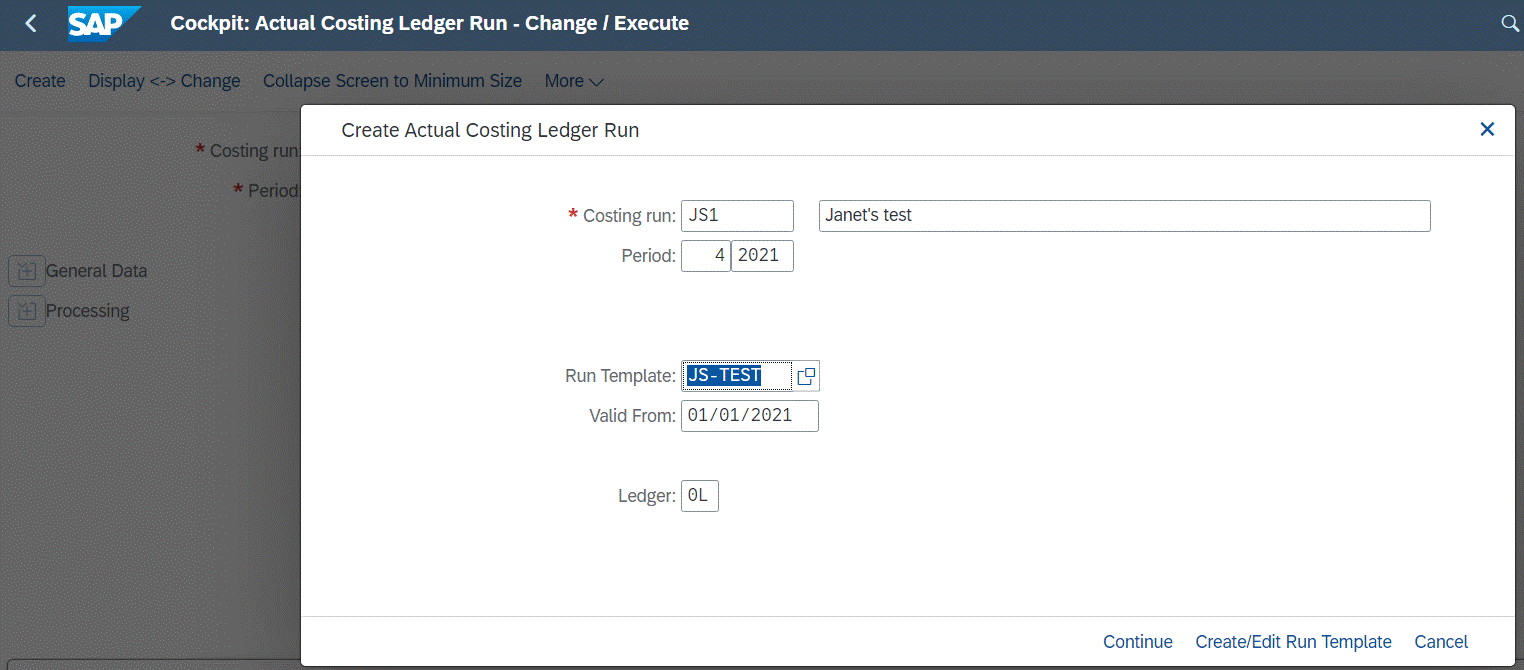
Figure 13: Ledger-Specific Costing Run for Actual Costing
Balance Sheet Valuation
With UPA, inventory balance sheet valuation can be performed separately by ledger. Ledger-specific valuation alternatives allow inventory values to reflect the accounting principles assigned to each ledger. Figure 14 provides an overview of the inventory balance sheet valuation functions available with Universal Parallel Accounting.
Release-specific restriction: SAP’s S/4HANA 2025 FPS01 UPA documentation states that inventory prices for FIFO valuation and lowest-value determination based on market prices can only be processed for the leading ledger. Ledger-specific valuation alternatives do not mean that every valuation method updates every ledger. Verify the supported scope for your release.
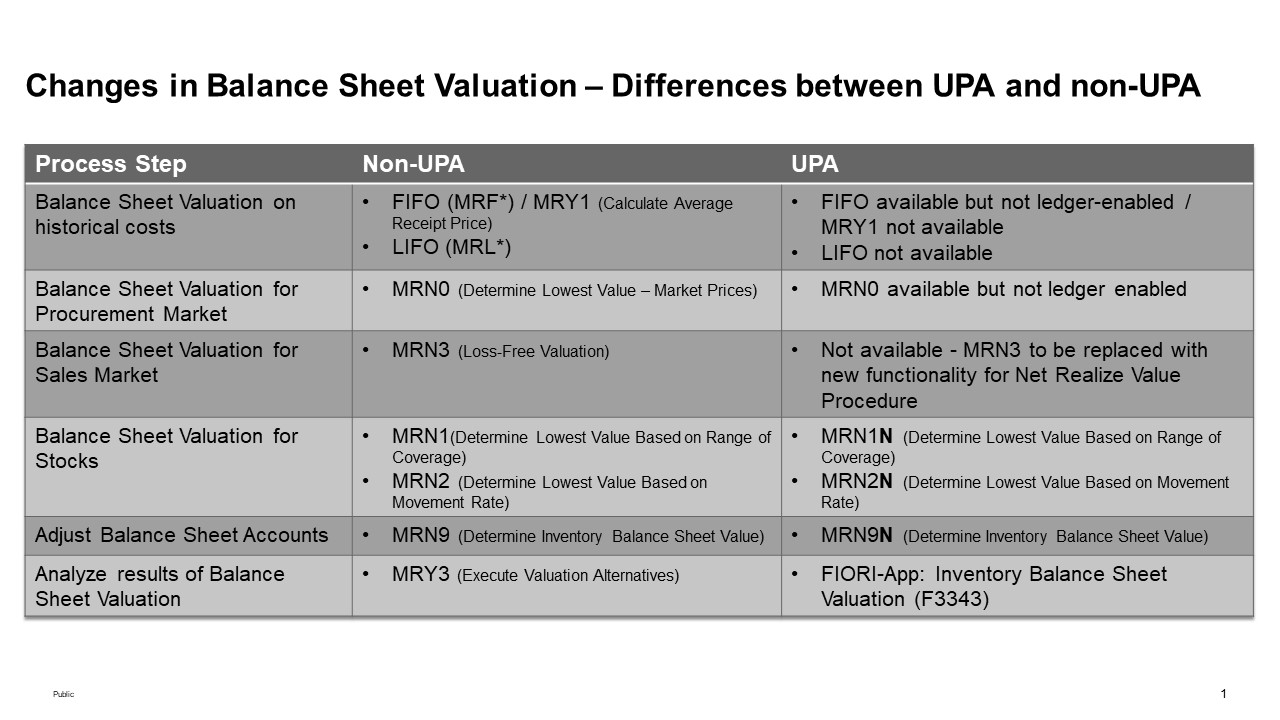
Figure 14: Balance Sheet Valuation Methods
With UPA, inventory balance sheet valuation is managed using ledger-specific valuation alternatives. These alternatives represent valuation methods such as lowest value by market price, range of coverage, movement rate, FIFO, and inventory costing. Figure 15 shows how valuation alternatives are assigned to individual ledgers, allowing inventory valuation to reflect the accounting principles represented by each ledger.
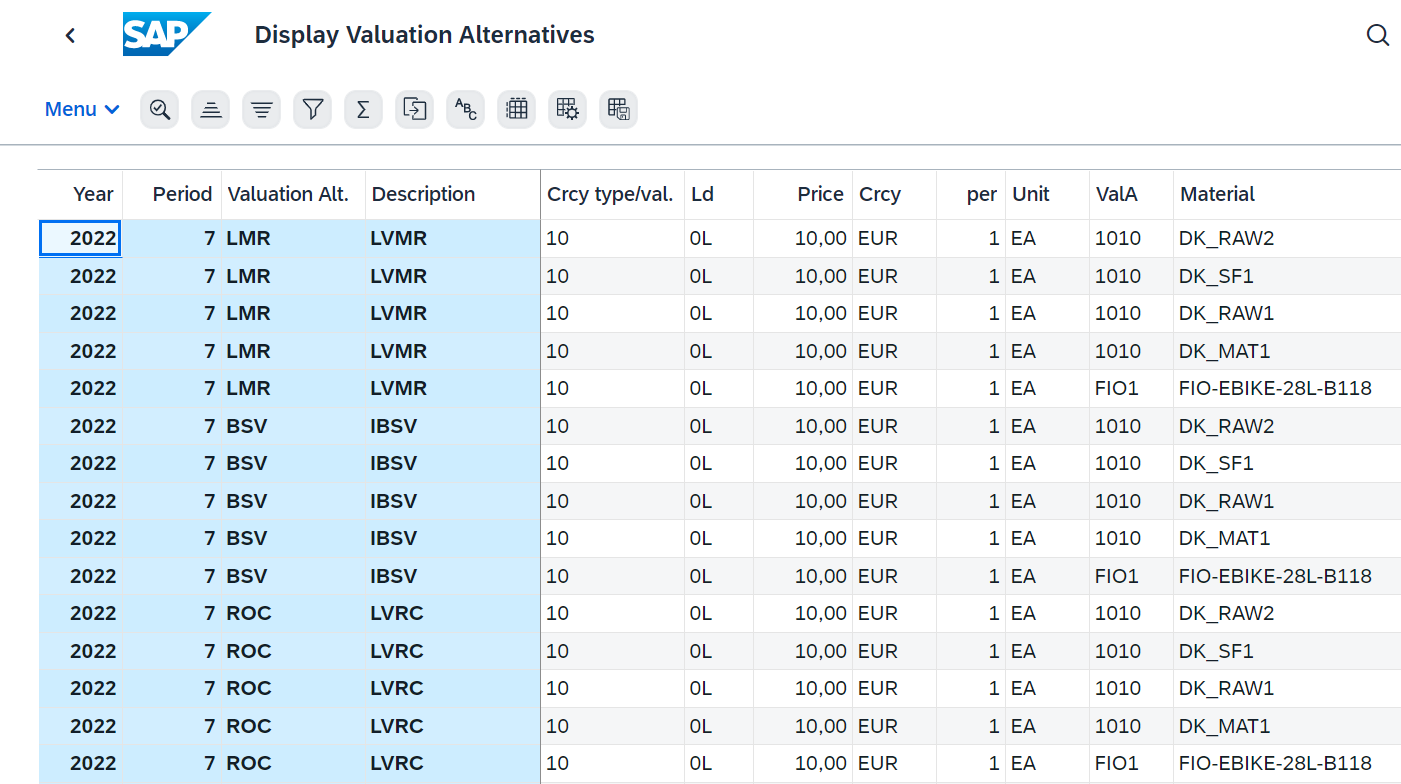
Figure 15: Valuation Alternatives App
The results of the inventory balance sheet valuation calculations can be used to adjust inventory values by ledger. The Adjust Inventory Balance Sheet Accounts – Delta Posting app (MRND) posts the difference between the inventory value and the calculated balance sheet value, as shown in Figure 16. Alternatively, the Adjust Inventory Balance Sheet Accounts – Price Change app (MRNP) can be used to update material prices.
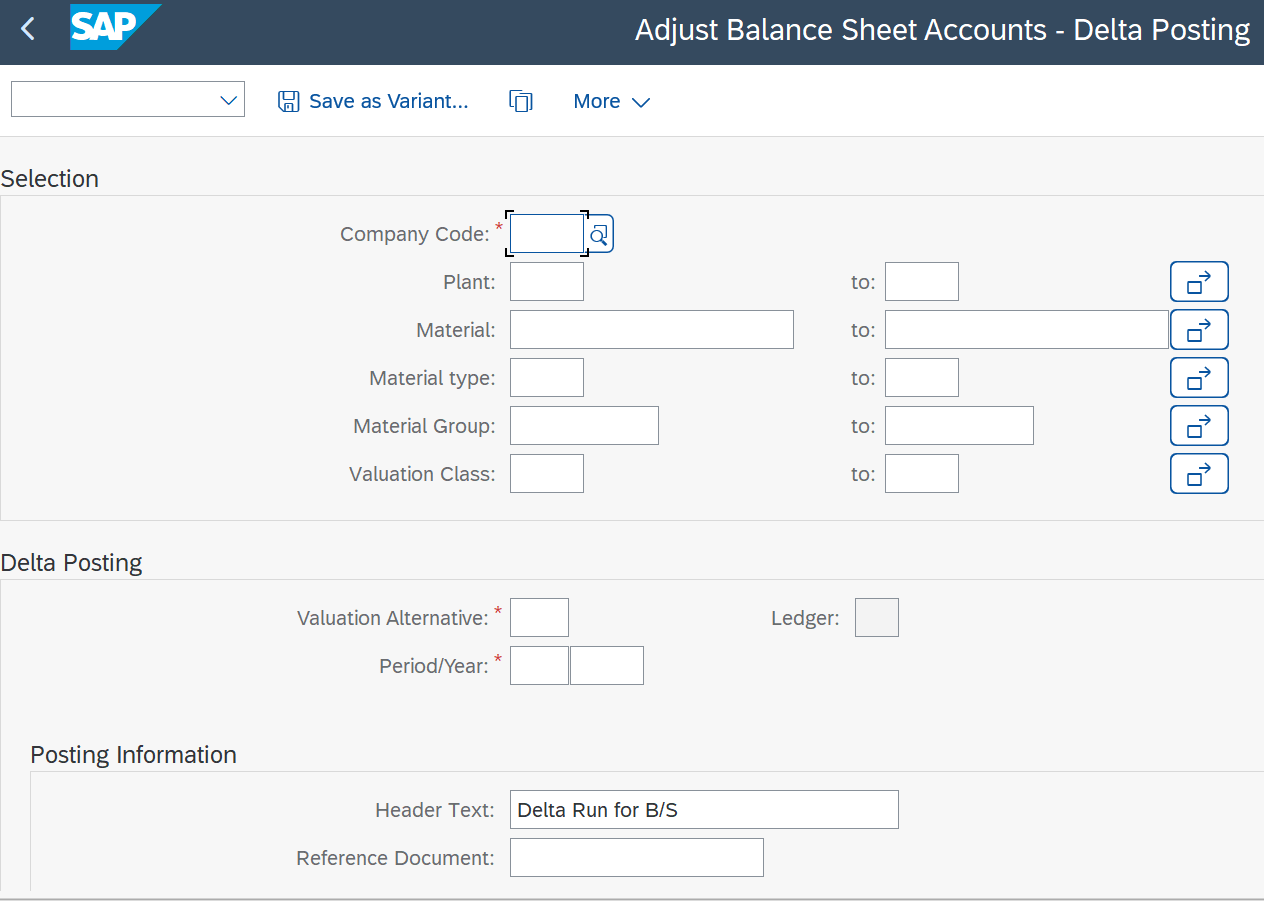
Figure 16: Adjust Balance Sheet Accounts
Finally, the balance sheet valuation results can be displayed in the Inventory Balance Sheet Valuations app, as shown in Figure 17. Notice the fields Valuation Alternative and Ledger in the selection screen.
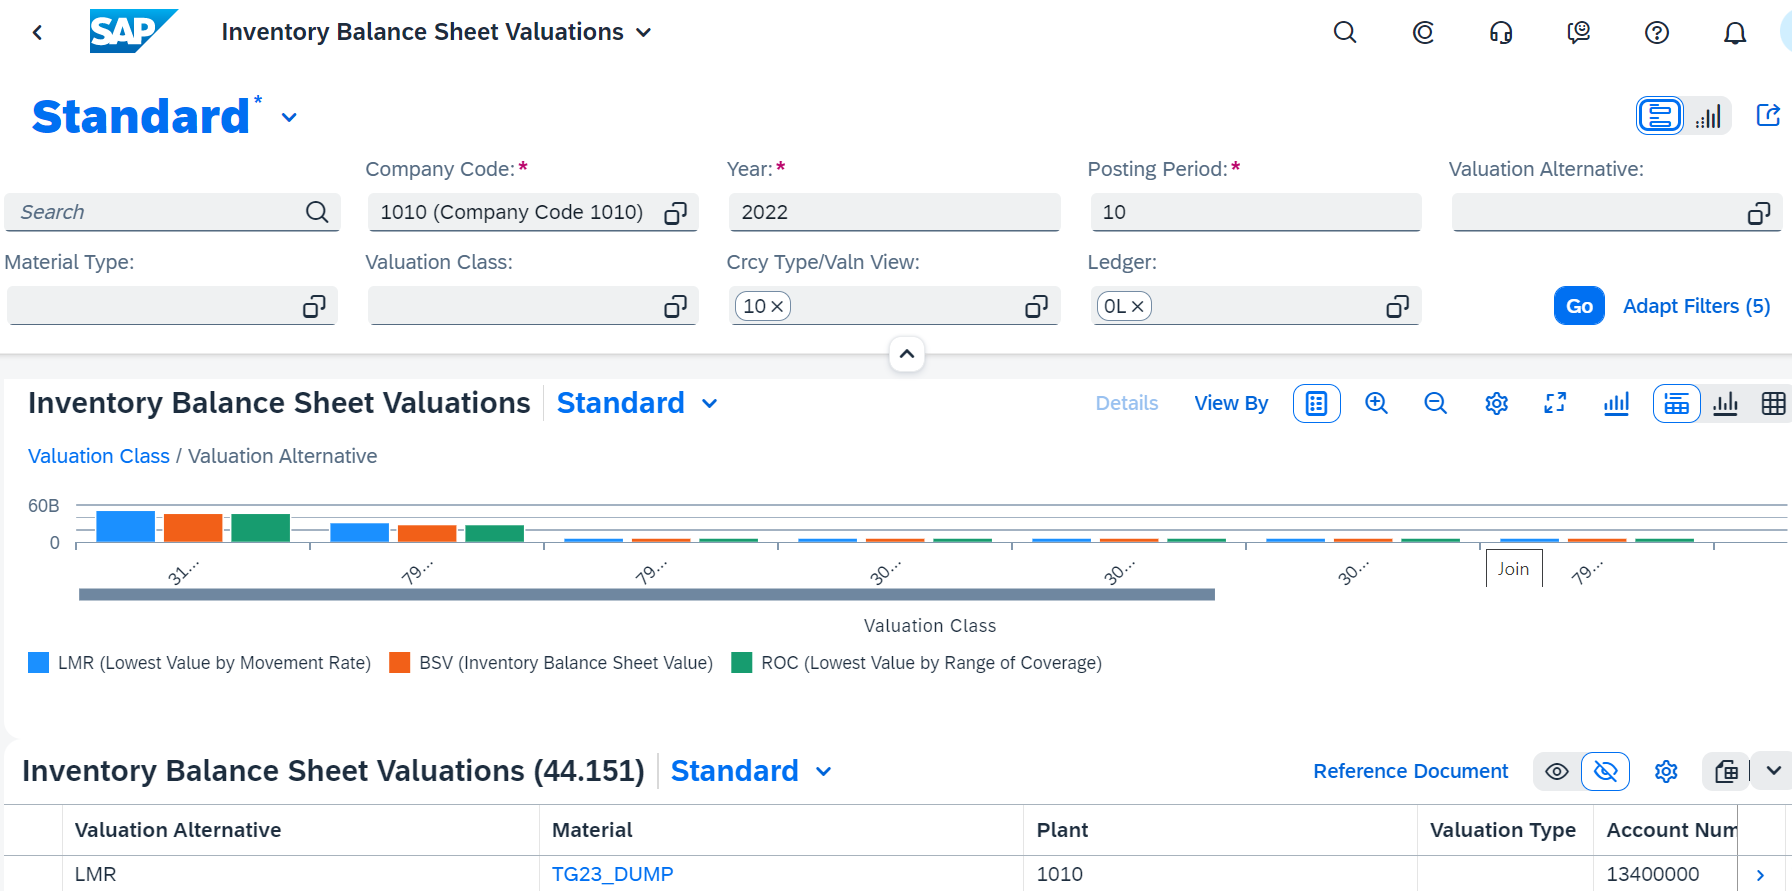
Figure 17: Inventory Balance Sheet Valuations app
Conclusion
Universal Parallel Accounting simplifies parallel accounting by enabling many financial processes to be calculated and posted by ledger. For inventory accounting, this supports ledger-specific material prices, standard costs, actual costs, and balance sheet valuations, helping organizations reflect different accounting principles within a common SAP S/4HANA framework.
UPA can be implemented in a new system or migrated into an existing SAP S/4HANA system, provided the relevant prerequisites are met. Existing systems require prechecks and a migration project before UPA can be activated. Because activation affects multiple financial and controlling processes and cannot be reversed, organizations should evaluate the supported scope and migration requirements carefully before implementation.
For current information about UPA scope, availability, and restrictions, refer to SAP Note 3191636 and the latest Universal Parallel Accounting documentation in the SAP Help Portal.
Turn SAP Cost Data into Better Business Decisions
Unexplained variances? Unclear product margins? ERPCorp helps you uncover cost drivers, improve inventory valuation, and simplify SAP period-end closing—with practical expertise in Product Costing, Material Ledger, and S/4HANA Finance.
Glossary
Accounting Principle
The accounting rules, such as IFRS or local GAAP, used to prepare financial information. UPA supports parallel accounting principles through ledger-specific processes.
Actual Costing
A Material Ledger process that calculates actual material costs using recorded costs and price differences. With UPA, actual costing is processed through ledger-specific runs.
Company Code Currency
The local currency assigned to a company code. Currency and valuation type 11 represents group valuation in company code currency.
Group Currency
A currency used for group-wide reporting. Currency and valuation type 31 represents group valuation in group currency.
Group Valuation
A valuation perspective that measures relevant value flows at group cost, excluding intercompany profit. It does not replace complete statutory consolidation.
Ledger
A set of accounting records used to represent an accounting principle or valuation perspective. UPA uses separate single-valuation ledgers for legal, group, and profit center valuation where supported.
Ledger Run
A ledger-specific actual costing run. A single-period run calculates actual prices for one period; a year-to-date run calculates cumulative actual prices.
Legal Valuation
The valuation perspective of an individual legal entity, including the transfer prices charged in intercompany transactions.
Material Ledger
The SAP component supporting material valuation in multiple currencies and valuation views. Material Ledger is mandatory in SAP S/4HANA; Actual Costing is optional.
Profit Center Valuation
A valuation perspective using transfer prices for goods exchanged between profit centers. It is available with UPA from SAP S/4HANA 2023 and uses a separate ledger.
Standard Cost Estimate
A calculation of planned material, activity, and overhead costs. UPA supports standard costs by ledger and common standard costs across ledgers where configured.
Universal Parallel Accounting (UPA)
An SAP S/4HANA capability that extends ledger-specific accounting across financial and controlling processes, including inventory valuation, product costing, and actual costing.
Continue Learning with SAP PRESS
Explore John Jordan's SAP PRESS books covering Product Costing, Finance, Controlling, and SAP S/4HANA, with practical guidance for implementing and optimizing SAP financial processes.