Production Variance Analysis in SAP S/4HANA, by John Jordan and Janet Salmon, follows production costs from initial planning and standard cost estimates through actual postings, variance calculation, and reporting.
The seven chapters help SAP controllers and consultants trace where differences arise and understand how they affect product profitability. View the book at SAP PRESS.
The 2023 SAP PRESS edition builds on earlier editions published in 2007 and 2011. Chapters 1–6 use SAP S/4HANA 2021 on-premise examples. Chapter 7 covers event-based scenarios in SAP S/4HANA Cloud and the SAP S/4HANA 2022 context.
Chapter 1: Initial Planning
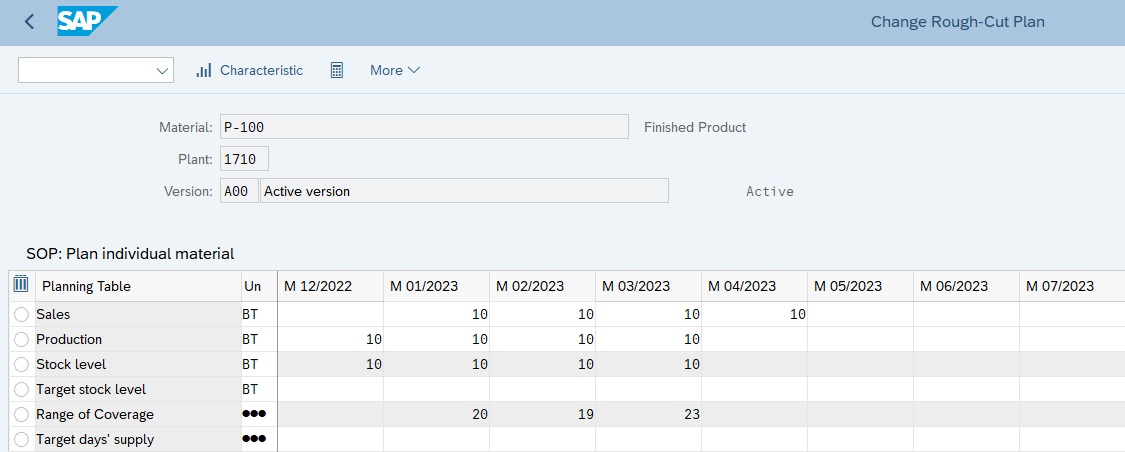
Planning sets the baseline for variance analysis. Figure 1 shows sales and operations planning. The chapter also covers long-term planning for material and capacity requirements, production versions that link bills of material (BOMs) and routings, and planned activity rates derived from cost center expenses and activity volumes.
Chapter 2: Cost Estimates
A standard cost estimate combines data from the material master, BOM, routing, and work center, as shown in Figure 2. The chapter explains how costing sheets apply overhead and how cost components and the costing variant shape the estimate.

We show how to create and release a cost estimate for one material, use a costing run for multiple materials, and use mixed costing when a material has multiple production or procurement alternatives.
Chapter 3: Actual Costs
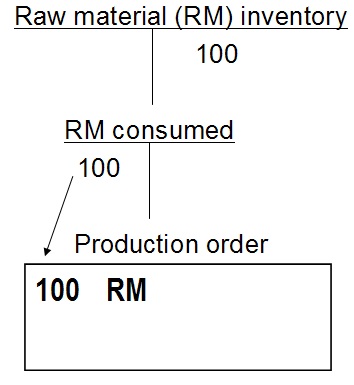
We introduce the Universal Journal and show how goods issues and activity confirmations post actual costs to production and process orders. Figure 3 illustrates a goods issue posting.
The book introduces two SAP Fiori apps for manufacturing variance analysis: Production Cost Analysis (F1780) and Analyze Costs by Work Center/Operation (F3331). An order-level view highlights orders with differences. A work center or operation view helps narrow down where those differences arose.
Chapter 4: Period-End Processing
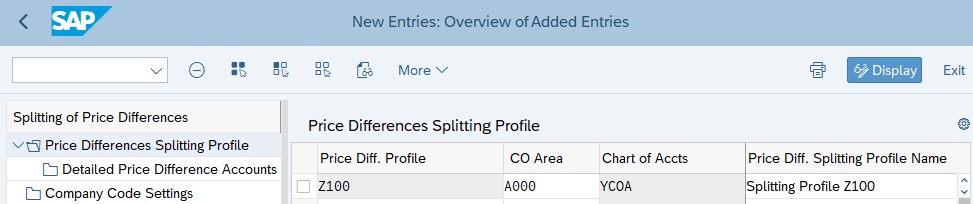
We walk through period-end overhead, work in process (WIP), variance calculation, and settlement. The chapter explains how production variance categories help identify the sources of differences. Figure 4 shows a variance splitting profile used to assign variance categories for financial reporting. See the companion guide to SAP variance split in S/4HANA.
The chapter also explains how Actual Costing with SAP Material Ledger can roll eligible purchase and production differences through manufacturing levels.
Chapter 5: Scrap Variance
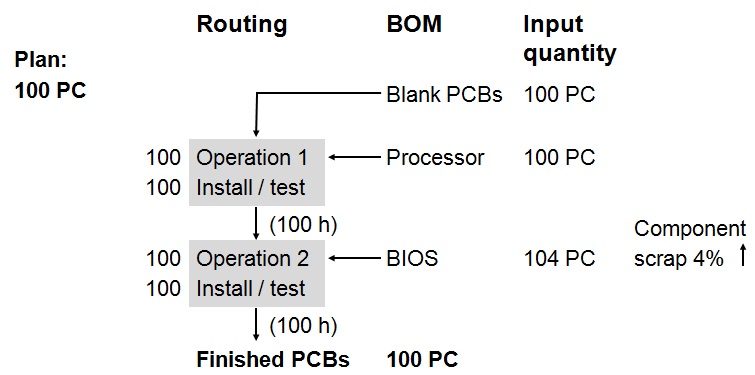
Assembly, component, and operation scrap affect planned quantities in different ways. Figure 5 illustrates how planned component scrap increases the input quantity. The examples show how to interpret the resulting scrap differences.
Chapter 6: Reporting
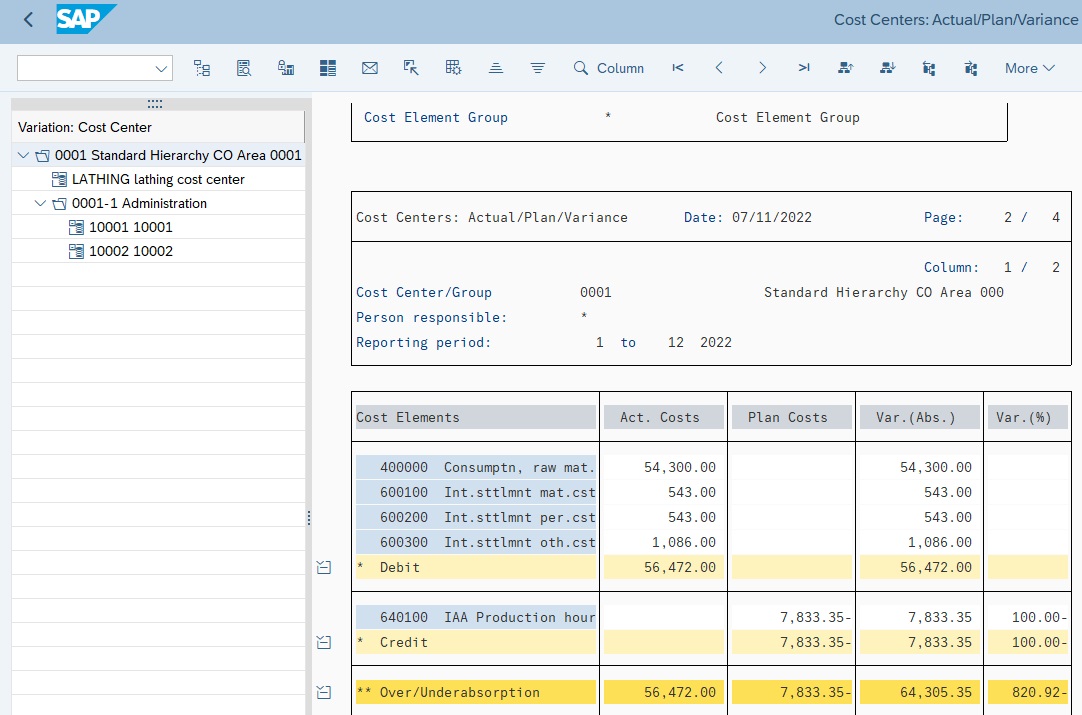
Reporting connects variance amounts to their causes and to product profitability. We compare classic cost center and product drilldown reports with SAP Fiori options. Figure 6 shows an example of standard cost center reporting.
Chapter 7: Future Direction of Variance Analysis
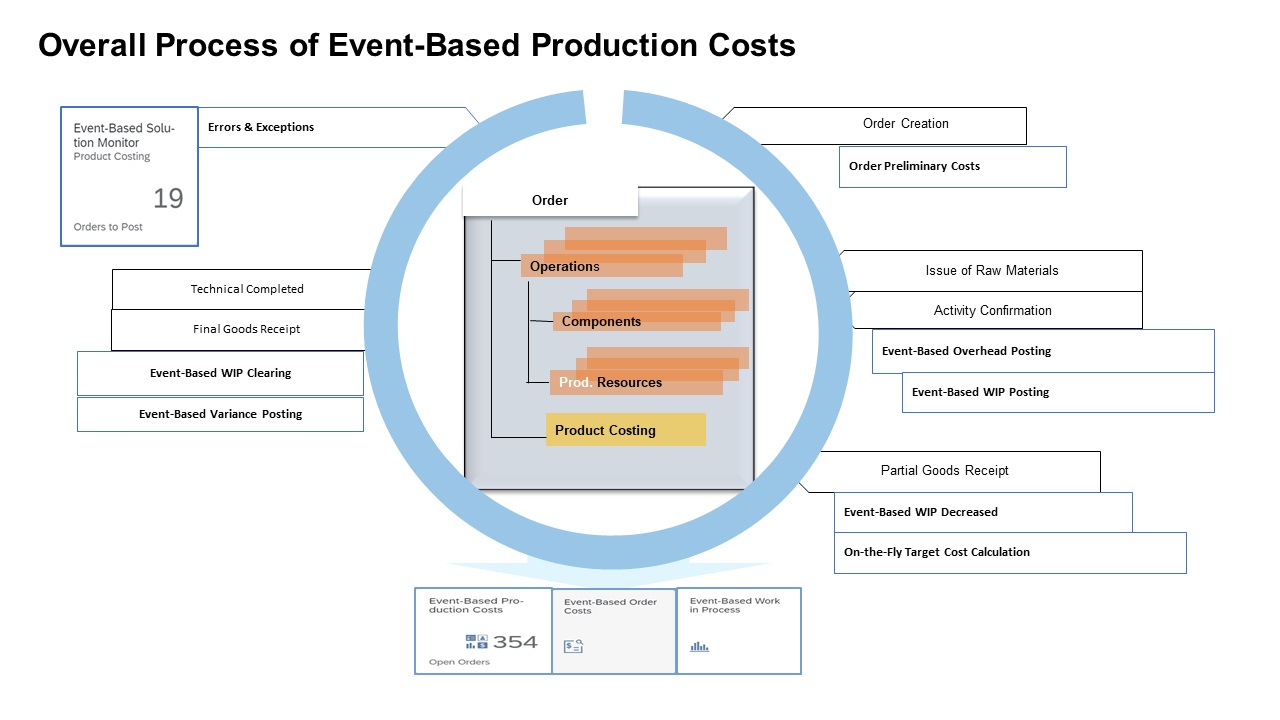
Chapter 7 introduces Event-Based Production Accounting in SAP S/4HANA. Supported events can trigger follow-on WIP and variance postings, bringing accounting results closer to the underlying production transactions. Figure 7 shows the event-based production cost cycle.
The book discusses SAP S/4HANA Cloud scope item 3F0, Event-Based Production Cost Posting, and the Universal Parallel Accounting scenario in SAP S/4HANA 2022. Check your edition, release, and manufacturing scenario before applying the configuration examples.
Get the SAP PRESS Book
 Use the book’s configuration examples and reporting walkthroughs to follow production variances from the shop floor to Finance.
View Production Variance Analysis in SAP S/4HANA at SAP PRESS
Glossary
Production Variance
A difference between actual production costs and the applicable target costs. SAP variance categories help explain the source of the difference.
Target Cost
A cost benchmark calculated for the relevant output or activity level and used in variance analysis.
Variance Split
The assignment of production variance categories to designated G/L accounts for financial reporting.
Work in Process (WIP)
The value of production still in progress, measured under the applicable costing and accounting rules.
SAP Controlling Conference